MPOT vs MUFB vs Separate Titles: Which Structure Suits Your Investment?
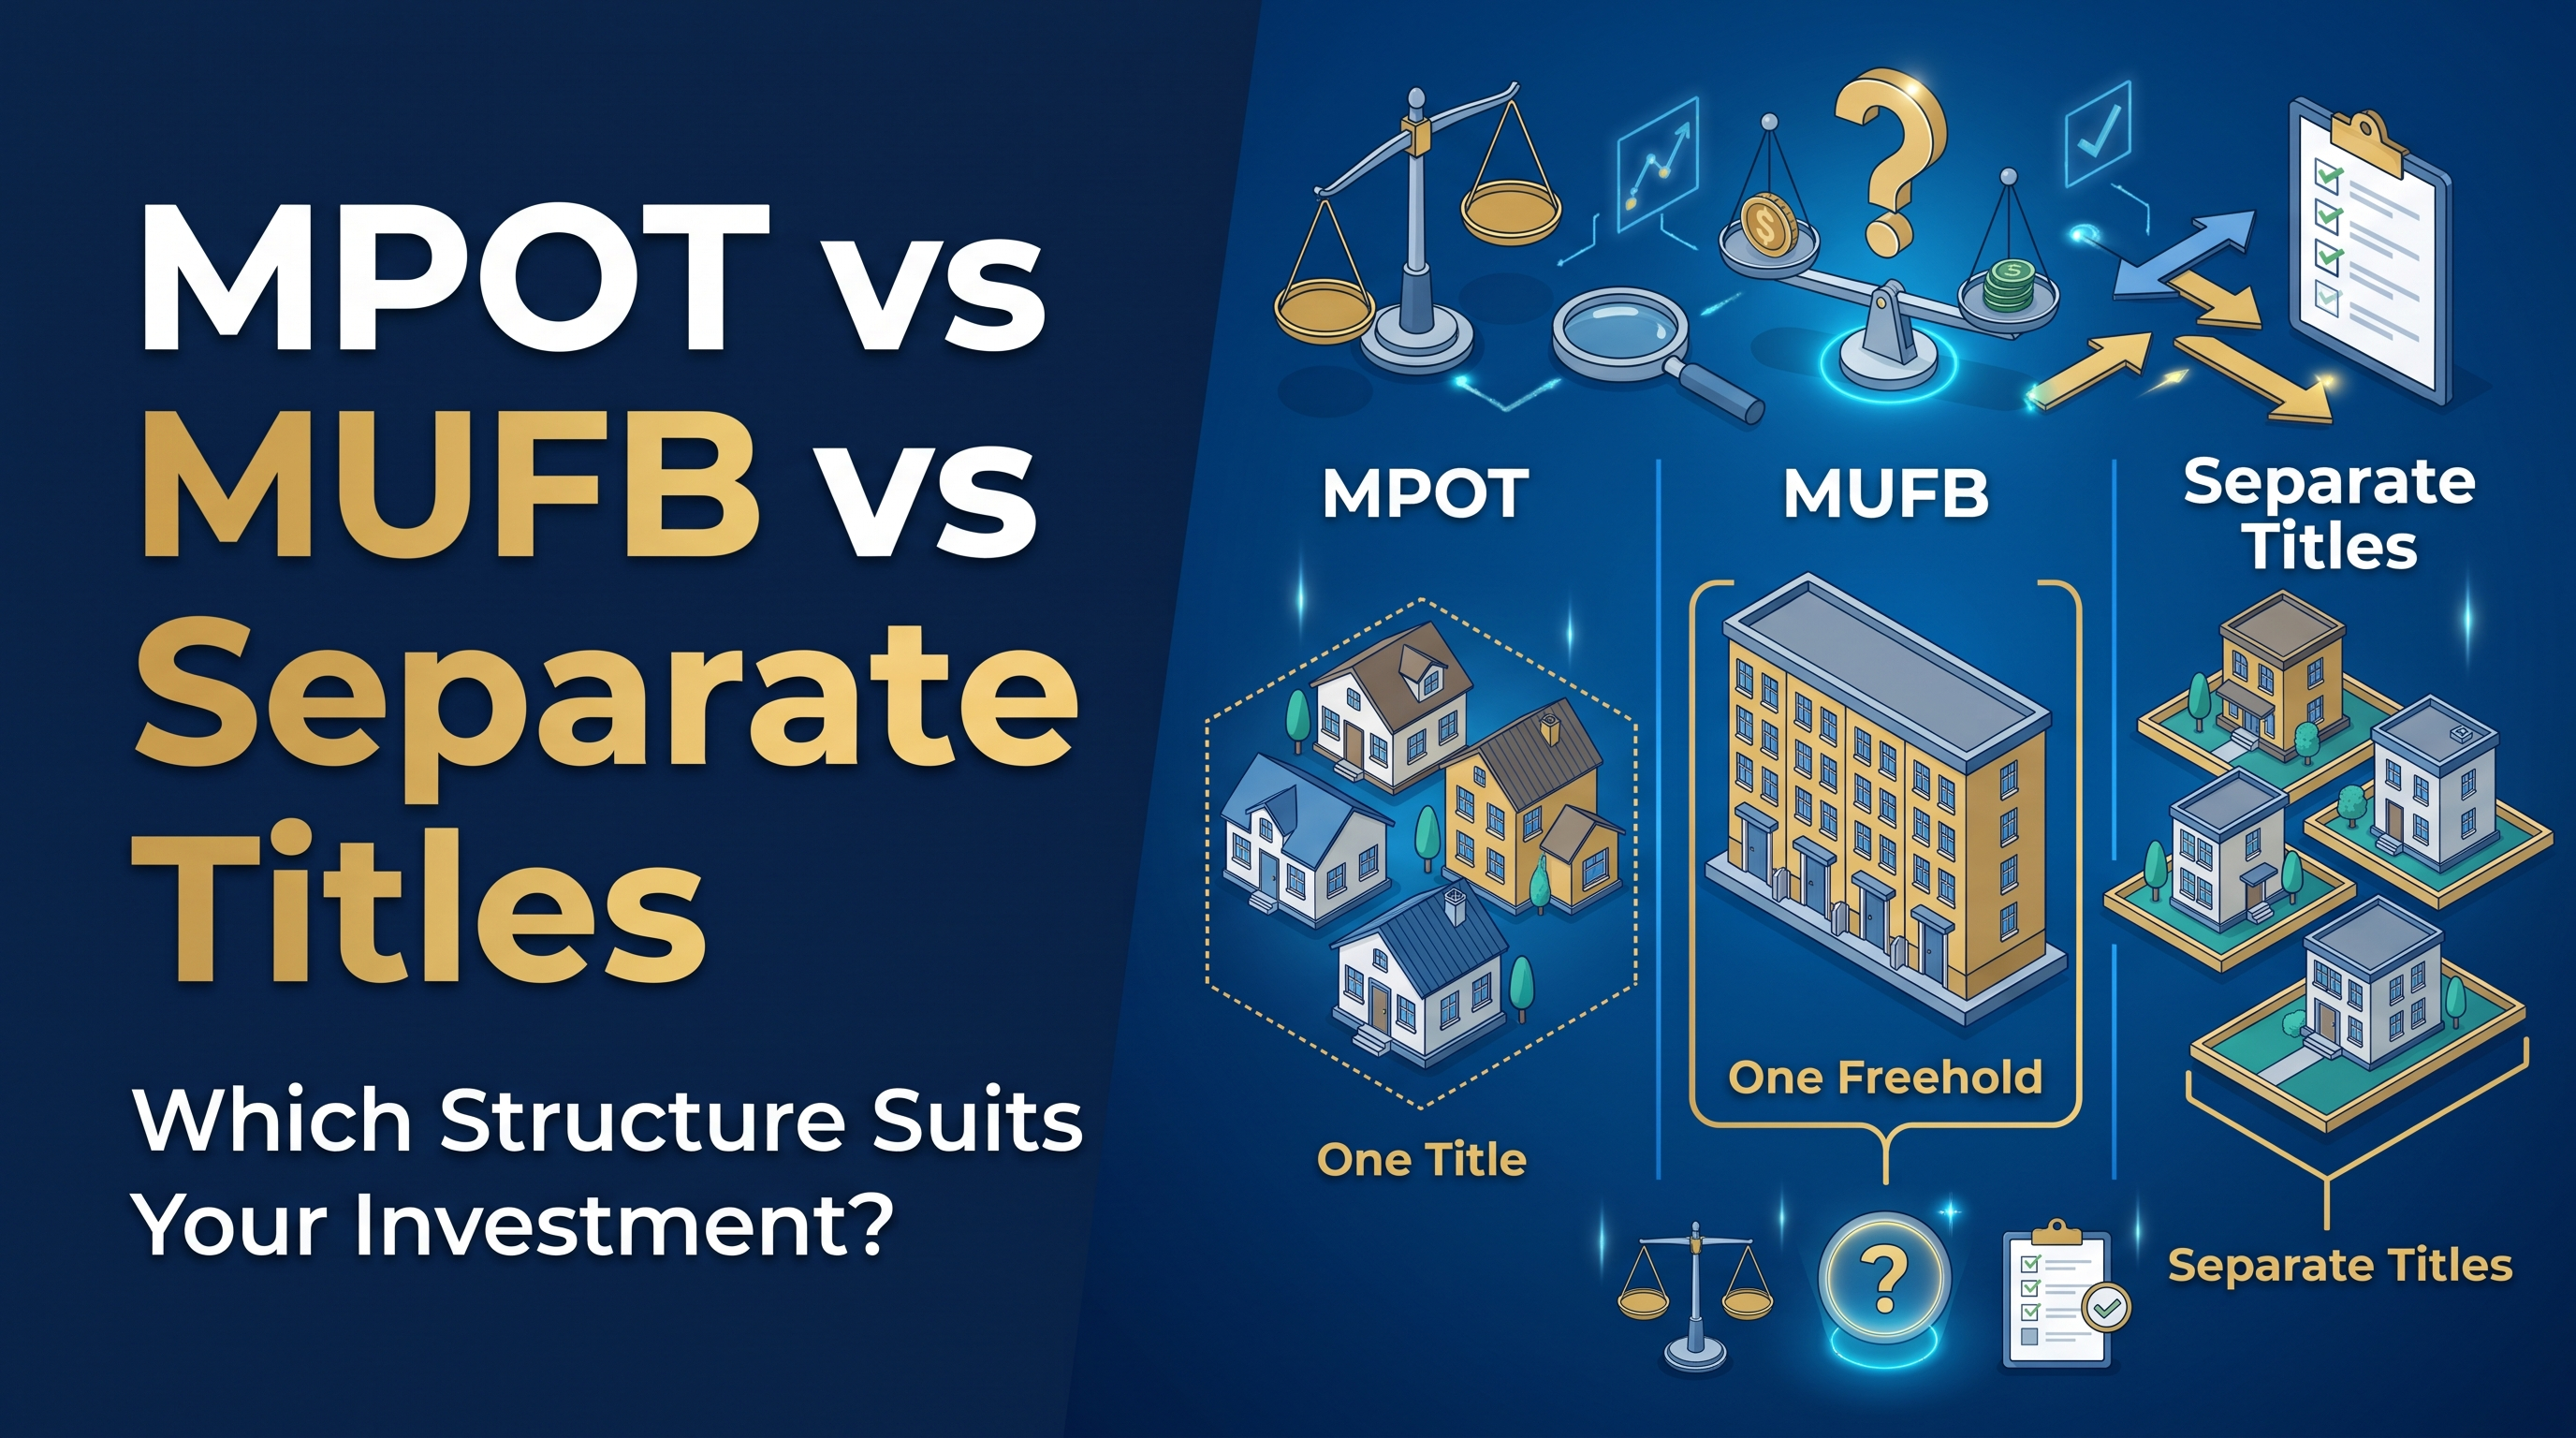
When you buy several rental units in one go, the way they are held on the title shapes everything that follows: which lenders will finance them, what they are worth, how easily you can sell, and how much paperwork you carry. Here is how the three main structures compare.
The three structures
MUFB (multi-unit freehold block): one building divided into self-contained flats, all on one freehold title. https://www.dynesourcer.co.uk/blog/complex-btl/mufb-mortgage-multi-unit-freehold-block https://www.dynesourcer.co.uk/blog/complex-btl/buying-block-of-flats-mufb-stamp-duty-title-split
MPOT (multiple properties on one title): separate dwellings, often separate buildings, sharing one freehold title. https://www.dynesourcer.co.uk/blog/complex-btl/mpot-mortgage-multiple-properties-one-title
Separate titles: each house or flat has its own registered title, freehold or leasehold, and is mortgaged individually.
Side by side
Lender choice is specialist for MUFB, narrowest for MPOT, and widest for separate titles. Number of mortgages: one for MUFB and MPOT, one per unit for separate titles. Valuation: discounted block or one-lot value for MUFB and MPOT; full value of each unit on separate titles. Selling one unit needs a lease or title split for MUFB and MPOT, and is straightforward on separate titles. Risk is concentrated on one title for MUFB and MPOT, and spread across units when titles are separate.
When each one makes sense
Choose MUFB or MPOT when the units are only available together on one title; you want one loan, one renewal date and one set of legal work; or you see value in splitting the title later and are prepared for the cost and time.
Choose separate titles when you want the widest lender choice and sharpest rates; you may sell units individually or refinance them at different times; or you prefer one weak property not to affect the borrowing on the others.
Stamp duty: structure rarely changes it
Whatever the structure, units bought from the same seller in one deal are usually taxed on the combined price, plus the 5% surcharge for additional homes. If the deal includes six or more dwellings, you can elect non-residential rates. Your conveyancer will confirm what applies.
Turning one title into many
Splitting an MUFB or MPOT into separate titles can unlock value and lender choice, but plan for:
1. Lender consent on the existing mortgage. 2. Legal work: new leases for flats, or transfers of part for houses, plus Land Registry plans. 3. Rights and services: access, drainage, utilities and shared areas need to be documented. 4. Building compliance: each unit must meet building regulations and fire safety standards. 5. Refinancing: some lenders want a period of ownership before lending on the new titles.
Compare all three
The complex BTL calculator lets you switch between MUFB and MPOT to compare rental cover on the same tool.
Compare MUFB and MPOT structures in the complex BTL calculator. HMO, MUFB, MPOT, short-term let, holiday let and other specialist property types all use this same tool.
https://www.dynesourcer.co.uk/mortgages/complex-buy-to-let-mortgage-calculator
For standard single-let buy-to-let mortgages:
https://www.dynesourcer.co.uk/mortgages/buy-to-let-mortgage-calculator
FAQs
Which structure gets the cheapest mortgage
Usually separate titles, because more lenders compete.
Can I buy an MUFB and finance it as separate flats
Only after the title is split and leases are registered.
Is MPOT riskier than MUFB
Both concentrate risk on one title. MPOT has fewer lenders, which can make refinancing harder.
Does a limited company help
Many block and MPOT buyers use an SPV, but it depends on your tax position: https://www.dynesourcer.co.uk/blog/complex-btl/limited-company-buy-to-let-mortgage-2026
Important information
Your property may be repossessed if you do not keep up repayments on your mortgage. Most buy-to-let mortgages are not regulated by the Financial Conduct Authority. Consumer buy-to-let mortgages, and mortgages where you or a close family member will live in the property, are regulated. Dynesourcer Ltd is an Introducing Appointed Representative of Dynamic Commercial Finance Ltd, which is authorised and regulated by the Financial Conduct Authority, FRN 946483. A broker fee may be payable on application; we will tell you the amount before you proceed. This article is general information, not personal advice or tax advice. Tax treatment depends on your individual circumstances and may change. Figures correct as at 29 October 2026.
Want tailored sourcing?
Use the calculator for your scenario, then move into sourcing to compare, shortlist and apply.