Bridging to Buy-to-Let: How the Buy, Refurbish, Refinance Strategy Works
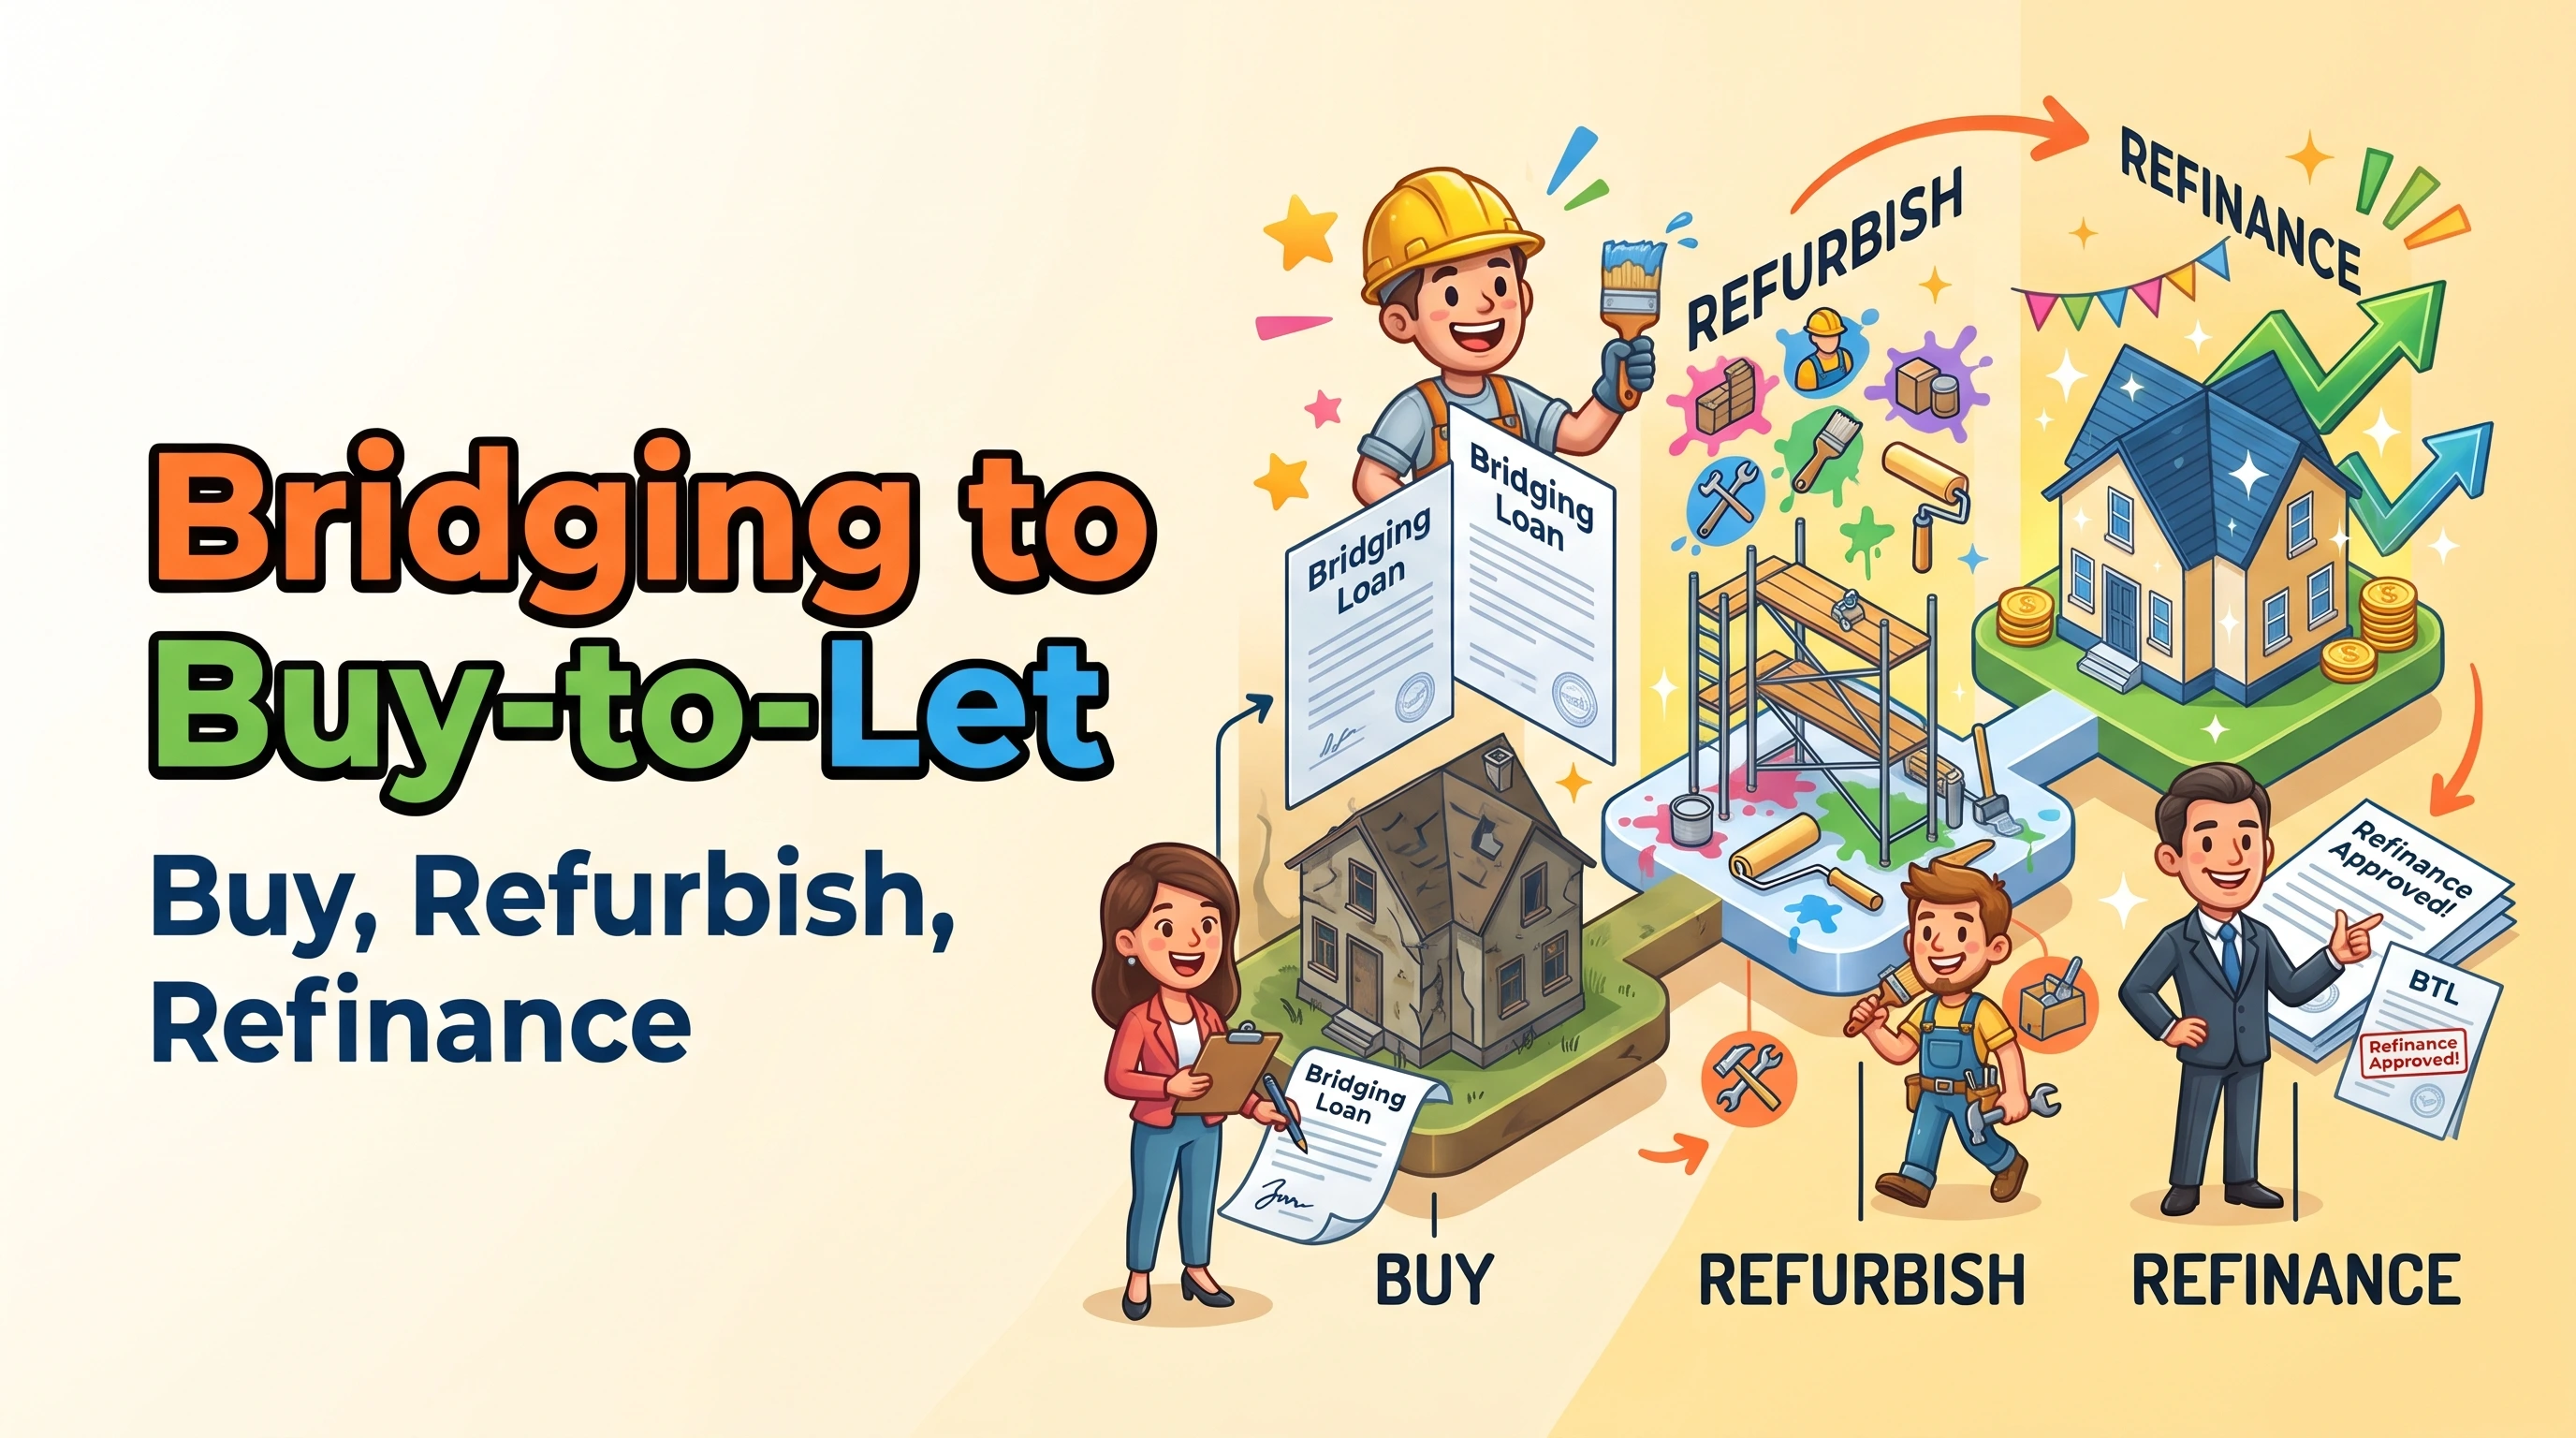
Some of the best-value properties can't be bought with a standard buy-to-let mortgage. A house with no working kitchen, a derelict flat above a shop, or a property sold at auction with a 28-day completion deadline all fall outside mainstream lending. Investors use bridging finance to buy and refurbish, then refinance onto a buy-to-let mortgage at the new, higher value.
How the strategy works
1. Buy with bridging. A short-term loan, usually 6 to 18 months, often at up to 70% to 75% of the purchase price or current value. 2. Refurbish. Some bridging lenders release extra funds for works, either upfront or in stages. 3. Let the property on an assured periodic tenancy once it is habitable. 4. Refinance onto a buy-to-let mortgage based on the new value and rent, repaying the bridge. 5. Recycle capital. If the value has risen enough, some of your deposit comes back out for the next project.
What bridging costs
Bridging is priced monthly, not annually. Expect a monthly interest rate, an arrangement fee (often around 2%), an exit fee on some products, plus valuation and legal costs on both loans. Interest is usually rolled up or retained and repaid when the loan ends, so you are not making monthly payments during the works.
Because costs build each month, delays are expensive. A three-month overrun on works can wipe out much of the profit.
Planning the exit before you start
Your bridging lender will want a credible exit, and so should you. Before you buy, check:
• Ownership rules. Some buy-to-let lenders require you to own a property for six months before refinancing on the new value. Others offer "day one" or short-ownership remortgages, especially after a documented refurbishment. • The valuation. The new value must be supported by local sales evidence, not just the cost of works. • The rent. It must pass the buy-to-let rental cover test at the new loan amount: https://www.dynesourcer.co.uk/blog/complex-btl/buy-to-let-icr-stress-test-top-slicing • A plan B. If the refinance falls short, could you sell, or put in more cash?
Regulation and risk
Bridging for investment property is usually unregulated. If you or a close family member will live in the property, it becomes regulated bridging and must be arranged by an FCA-authorised adviser.
Bridging loans are secured on property and the full balance falls due at the end of the term. If you cannot repay or refinance, the lender can take possession and sell the property.
Plan the whole journey on Dynesourcer
We can help with both sides of the deal. Use the complex BTL calculator to test the refinance before you bid. For a standard buy-to-let exit, use the buy-to-let link below.
Compare bridging to buy-to-let in the complex BTL calculator. HMO, MUFB, MPOT, short-term let, holiday let and other specialist property types all use this same tool.
https://www.dynesourcer.co.uk/mortgages/complex-buy-to-let-mortgage-calculator
For standard single-let buy-to-let mortgages:
https://www.dynesourcer.co.uk/mortgages/buy-to-let-mortgage-calculator
FAQs
How quickly can a bridging loan complete
Often within two to four weeks; sometimes faster for straightforward cases.
Can I bridge at auction
Yes. Bridging is widely used to meet auction completion deadlines.
When can I refinance onto a buy-to-let
Some lenders allow it straight away after works, others after six months.
Do I need experience
Lenders prefer it, especially for heavy refurbishments, but light refurbishments are open to newer investors.
Important information
Your property may be repossessed if you do not keep up repayments on your mortgage. Most buy-to-let mortgages are not regulated by the Financial Conduct Authority. Consumer buy-to-let mortgages, and mortgages where you or a close family member will live in the property, are regulated. Dynesourcer Ltd is an Introducing Appointed Representative of Dynamic Commercial Finance Ltd, which is authorised and regulated by the Financial Conduct Authority, FRN 946483. A broker fee may be payable on application; we will tell you the amount before you proceed. This article is general information, not personal advice or tax advice. Tax treatment depends on your individual circumstances and may change. Figures correct as at 29 October 2026.
Bridging loans are short-term, secured loans. Your property may be repossessed if you do not repay or refinance the loan by the end of its term. Most bridging loans are not regulated by the Financial Conduct Authority.
Want tailored sourcing?
Use the calculator for your scenario, then move into sourcing to compare, shortlist and apply.