
Selective Invoice Finance (Spot Factoring) Explained
Not every business wants to commit its whole sales ledger to a finance facility. Sometimes you just need cash against one large invoice, or you want to try invoice finance before committing further. That's where selective invoice finance — also known as spot factoring — comes in.
What Is Selective Invoice Finance?
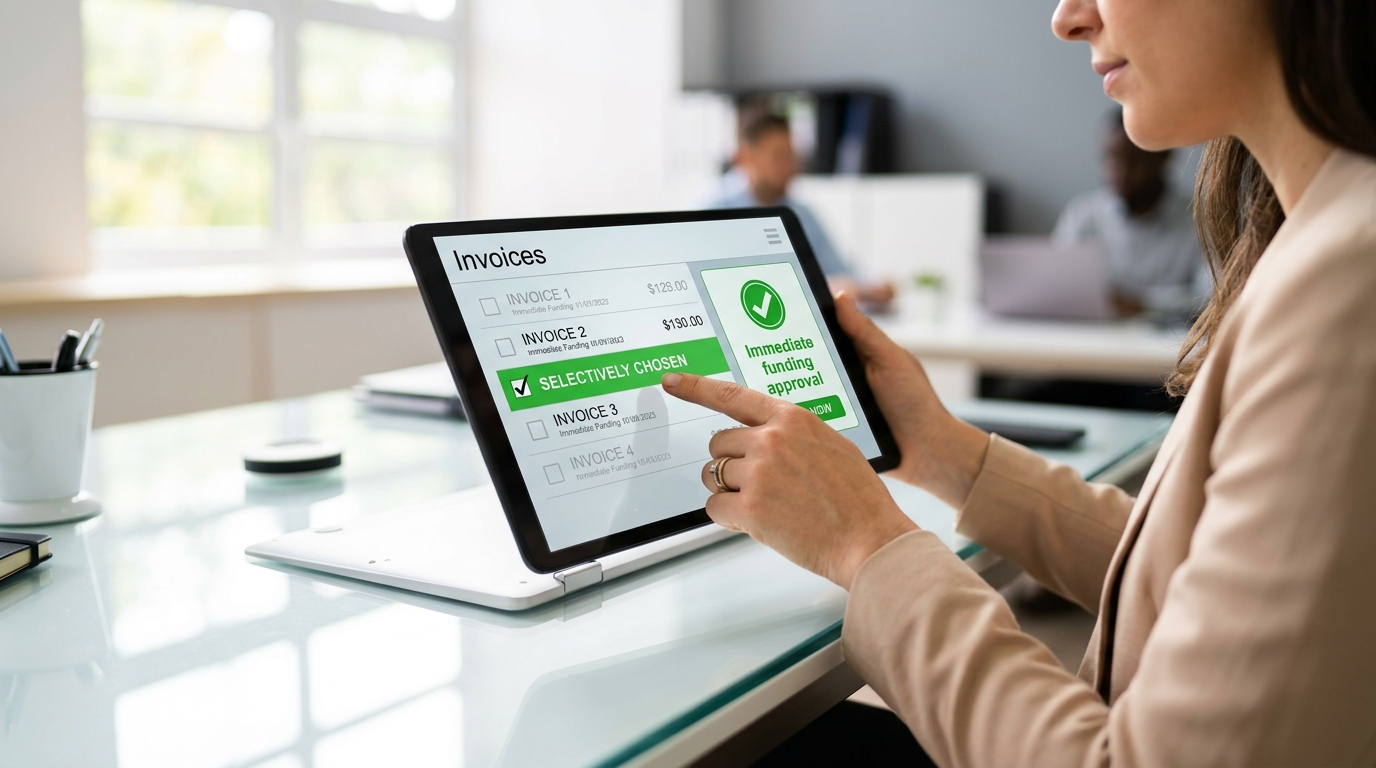
Selective invoice finance lets you fund individual invoices on a transaction-by-transaction basis, rather than committing your whole ledger. You choose which invoices to finance and when, which gives flexibility.
How It Works
You choose a specific invoice to finance. The lender advances a percentage of that invoice's value. Your customer pays as normal within the agreed terms. The balance, minus fees, is released once payment clears.
When Selective Invoice Finance Can Make Sense
Businesses with occasional large invoices rather than constant volume. Firms wanting to cover a one-off cash flow gap. Companies wanting to try invoice finance before a full facility. Seasonal businesses with uneven invoicing.
The Trade-Offs and Risks
Flexibility usually comes at a price. Single-invoice facilities often carry higher fees per invoice than a whole-ledger arrangement, though they typically have no minimum volume commitment. As with other invoice finance, terms may be recourse (you repay if the customer doesn't pay) and costs reduce the net amount you receive. For occasional use, the flexibility may outweigh the higher per-invoice cost — but compare carefully.
Compare Invoice Finance Options
Want the flexibility of financing invoices on demand? Dynesourcer can help you compare selective invoice finance options across the market: https://www.dynesourcer.co.uk/mortgages/invoice-finance-sourcing
Final Thoughts
Selective invoice finance is the flexible, lower-commitment option in the invoice finance world. If you only need funding occasionally — or want to test it first — spot factoring could be worth considering, provided the per-invoice cost stacks up.
Important information
Invoice finance for limited companies and LLPs is generally not FCA-regulated and typically falls outside the Consumer Credit Act 1974; sole traders/partnerships may have different protections. This article is not financial, legal or tax advice or a personal recommendation. Rates and figures are indicative and subject to change; finance is subject to status, eligibility and provider terms. Seek independent professional advice before entering any arrangement.
Want tailored sourcing?
Use the calculator for your scenario, then move into sourcing to compare, shortlist and apply.