
Invoice Finance vs Business Loans and Overdrafts
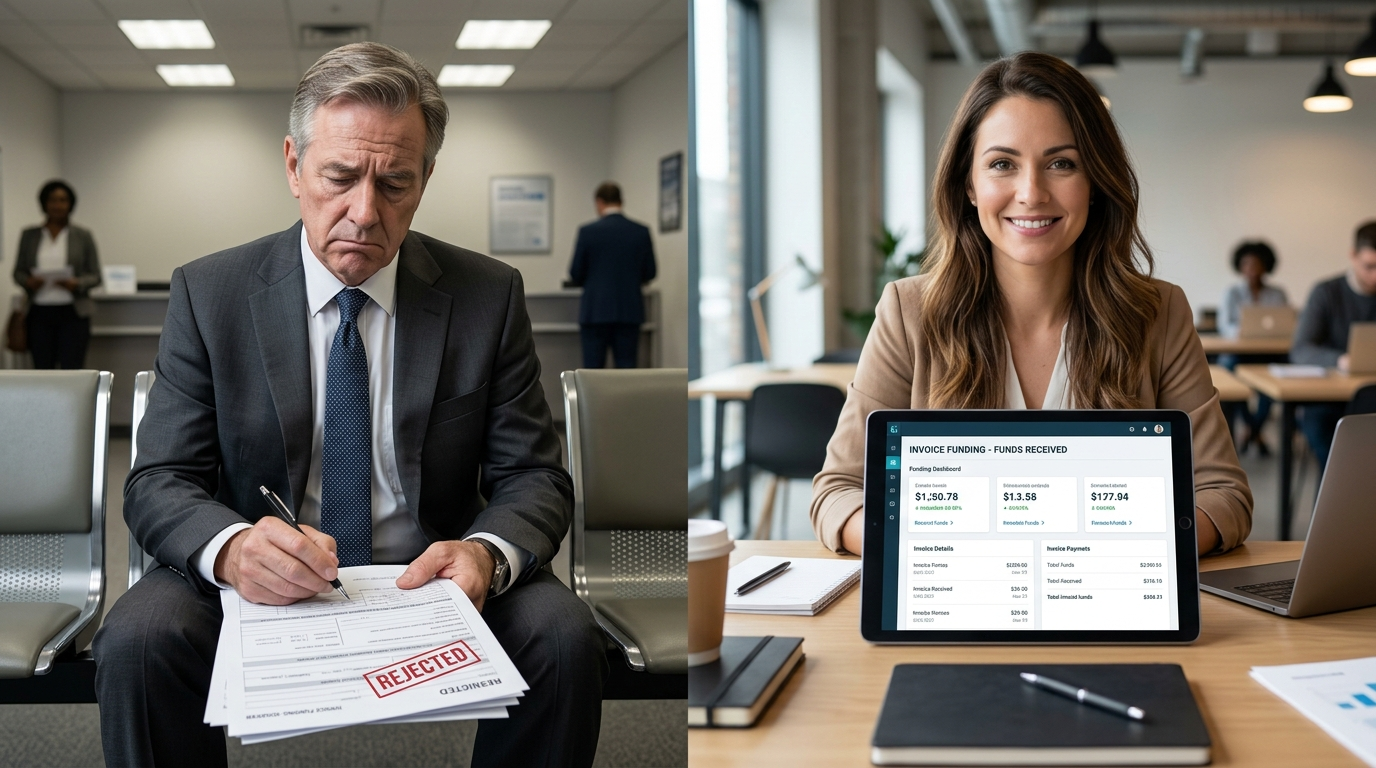
When cash is tight, many business owners think first of a loan or an overdraft. But for businesses that invoice other businesses, invoice finance can be an alternative worth comparing. Here's how the three differ.
Business Loans
A business loan gives you a fixed lump sum upfront, repaid over a set term with interest. Loans can suit one-off costs — equipment, expansion or stock. The trade-off for cash flow gaps is that the amount is fixed, repayments are set, and the loan may be secured against assets.
Business Overdrafts
An overdraft offers flexibility to dip into extra funds when needed. But limits are usually modest, can be reviewed or withdrawn by the bank, and don't automatically grow with your business. They can be a useful buffer rather than a scalable working capital solution.
Invoice Finance
Invoice finance advances cash against invoices you've already raised. Unlike a fixed loan, available funding can scale with your sales. It's designed specifically for the gap between doing the work and getting paid, though it carries its own fees and (often) recourse risk.
How to Choose
For a fixed, one-off purchase, a business loan often fits best. For a small, flexible safety net, an overdraft may be enough. For ongoing working-capital gaps caused by slow-paying customers, invoice finance may be the closest match. Many businesses use a combination. The right answer depends on your needs, costs and risk appetite — and different products carry different protections and regulation.
Compare Invoice Finance Options
If slow-paying customers are your main issue, invoice finance may be worth comparing against a loan or overdraft. Dynesourcer can help: https://www.dynesourcer.co.uk/mortgages/invoice-finance-sourcing
Final Thoughts
There's no one-size-fits-all answer. Loans, overdrafts and invoice finance solve different problems and carry different costs and risks. For B2B businesses waiting weeks to get paid, invoice finance is often worth considering alongside the alternatives.
Important information
Invoice finance for limited companies and LLPs is generally not FCA-regulated and typically falls outside the Consumer Credit Act 1974; sole traders/partnerships and some other products (e.g. certain loans) may carry different protections and regulation. This article is not financial, legal or tax advice or a personal recommendation. Rates and figures are indicative and subject to change; finance is subject to status, eligibility and provider terms. Seek independent professional advice before entering any arrangement.
Want tailored sourcing?
Use the calculator for your scenario, then move into sourcing to compare, shortlist and apply.