
Invoice Finance for Manufacturers
Manufacturing ties up cash at every stage — raw materials, labour and production costs are paid long before the finished goods are shipped and the invoice is finally settled. Invoice finance can help bridge that gap.
The Manufacturing Cash Flow Challenge
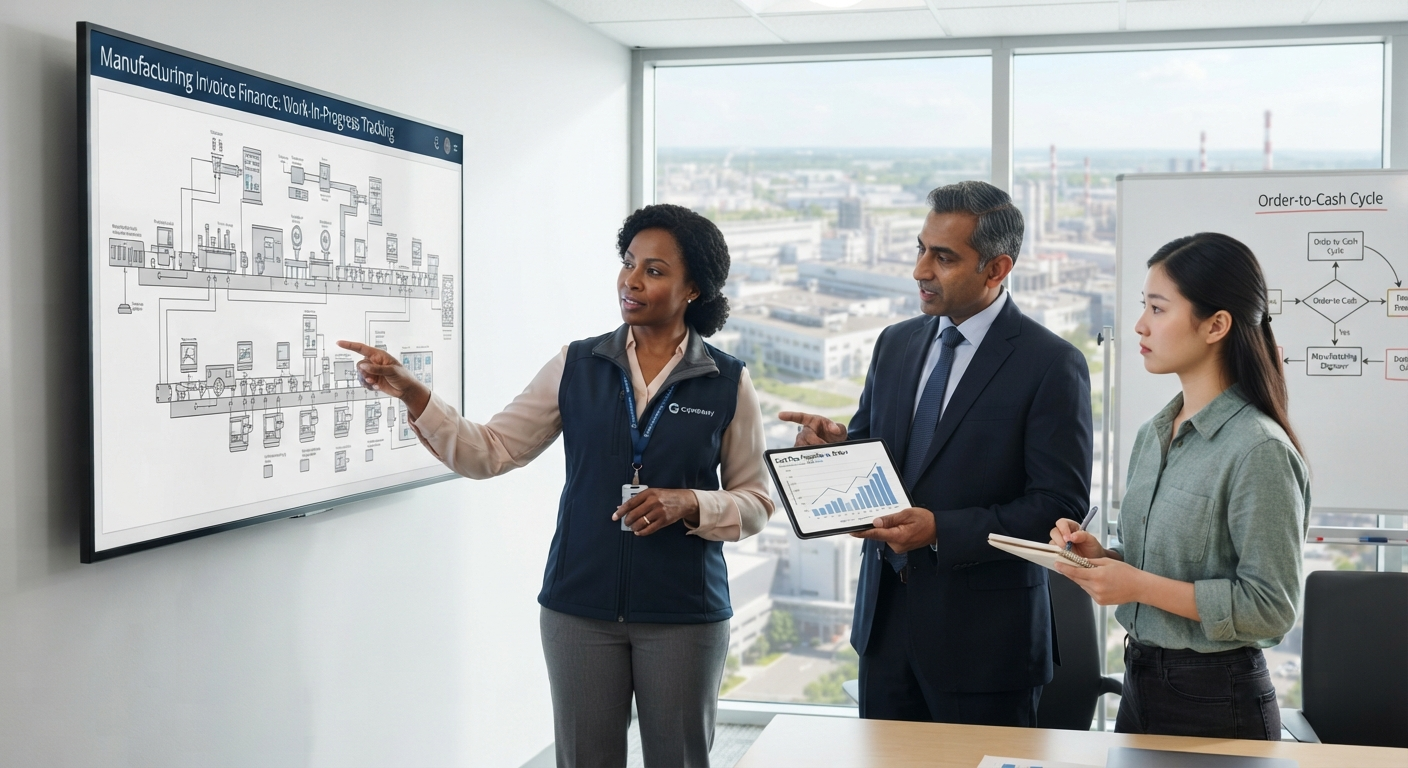
Manufacturers often buy materials in bulk, run production over weeks, then invoice on extended payment terms. That means significant cash is locked into work in progress and unpaid invoices at any given time, which can constrain the ability to take on new orders.
How Invoice Finance Can Help
Invoice finance releases much of an invoice's value soon after you raise it, freeing cash to buy materials, meet payroll and fund the next production run. For manufacturers with valuable stock and machinery, asset-based lending can go further — funding against inventory and equipment as well as invoices — for a larger overall facility.
Why It Can Suit Manufacturers
Funding that can scale with order volumes. Cash to buy materials and cover production upfront. Capacity to accept larger contracts. The option, via ABL, to unlock value from stock and machinery too.
Points to Consider
Costs (fees and interest) reduce net proceeds. Recourse terms mean you may repay advances for unpaid invoices. Work in progress and part-completed orders are treated differently by lenders. Sector-experienced providers understand manufacturing payment structures — match with one.
Compare Invoice Finance Options
Dynesourcer can help manufacturers compare invoice finance and asset-based lending options suited to the sector: https://www.dynesourcer.co.uk/mortgages/invoice-finance-sourcing
Final Thoughts
For manufacturers, cash flow shapes how much you can produce and how fast you can grow. Invoice finance — and ABL where appropriate — can help unlock the capital tied up in your operation, provided the terms suit your business.
Important information
Invoice finance and asset-based lending for limited companies and LLPs are generally not FCA-regulated and typically fall outside the Consumer Credit Act 1974; sole traders/partnerships may have different protections. This article is not financial, legal or tax advice or a personal recommendation. Rates and figures are indicative and subject to change; finance is subject to status, eligibility and provider terms. Seek independent professional advice before entering any arrangement.
Want tailored sourcing?
Use the calculator for your scenario, then move into sourcing to compare, shortlist and apply.