
The Cost of Invoice Finance: Fees and Rates Explained
One of the first questions businesses ask about invoice finance is: how much does it cost? The honest answer is that it depends — on your turnover, sector, customers and facility type. Once you understand the components, comparing providers becomes easier.
The Two Main Charges
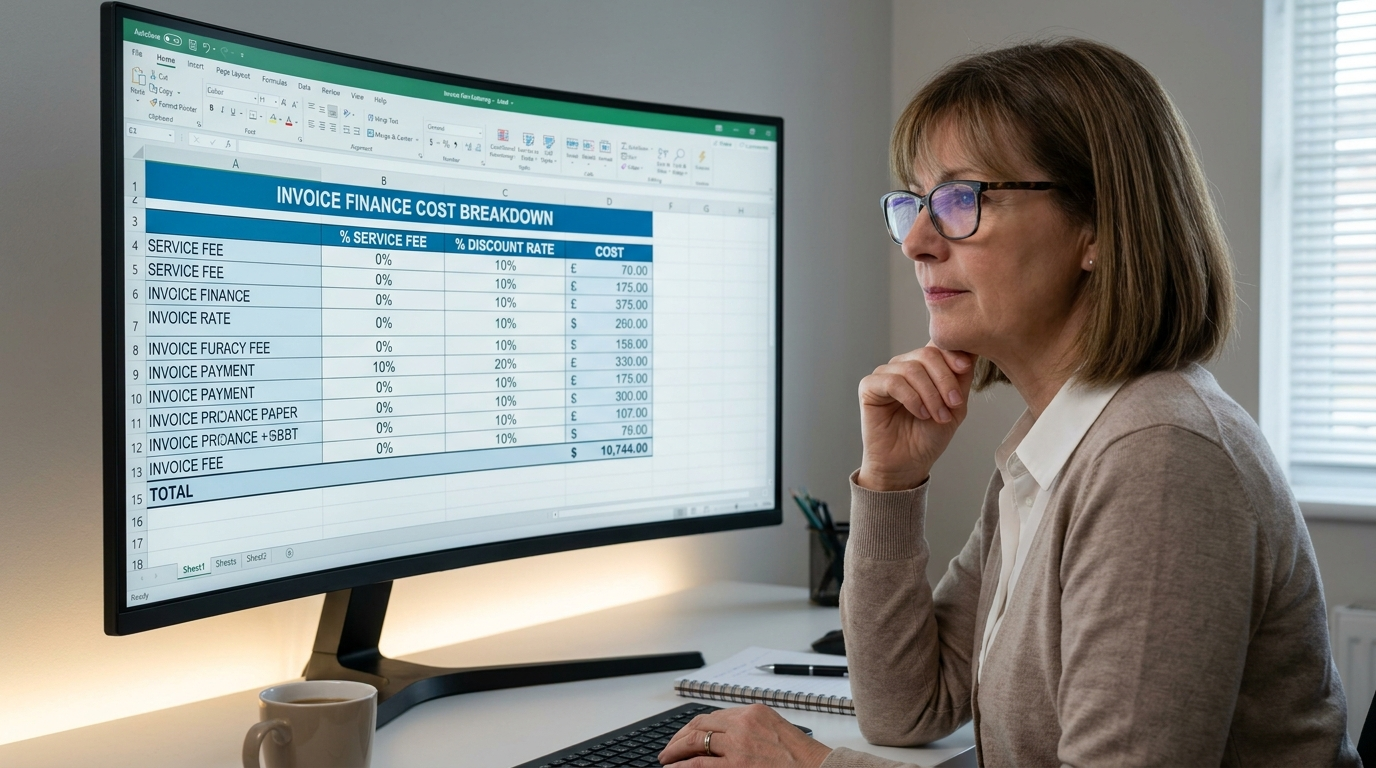
Most invoice finance costs come down to two elements. The service fee (or factoring fee) is typically charged as a percentage of turnover — often around 0.5% to 3% — and covers running the facility and, with factoring, collections. The discount charge is an interest rate applied to funds you draw down — usually the Bank of England base rate plus a margin of around 1.5% to 5%. (The base rate changes over time, so check the current rate when comparing.)
Watch for Additional Fees
Beyond the headline charges, some providers add arrangement or setup fees, minimum monthly fees, exit or termination charges, or charges for extra services such as bad debt protection. Always read the small print and compare the total cost, not just the advertised rate.
A Rough Illustration
As a general guide only, industry benchmarks suggest a business with around £500,000 turnover on typical payment terms might pay somewhere between roughly £5,000 and £15,000 a year for a facility. Larger, higher-volume businesses generally pay a lower percentage; smaller firms and one-off deals tend to pay more. Your actual cost will differ — treat this as illustrative, not a quote.
How to Compare Fairly
Ask each provider for a worked example based on your actual turnover and average payment terms, then compare the all-in cost — service fee, discount charge and any extras — rather than just the headline percentage.
Compare Invoice Finance Options
Dynesourcer can help you gather comparable quotes and see the total cost across providers: https://www.dynesourcer.co.uk/mortgages/invoice-finance-sourcing
Final Thoughts
Invoice finance has a cost — but weighed against missed growth, supplier penalties or more expensive short-term borrowing, it can still make sense. The key is comparing the total cost, not the headline rate, and checking it works for your business.
Important information
Invoice finance for limited companies and LLPs is generally not FCA-regulated and typically falls outside the Consumer Credit Act 1974; sole traders/partnerships may have different protections. All figures and rates above are indicative, correct at the time of writing and subject to change. This article is not financial, legal or tax advice or a personal recommendation; finance is subject to status, eligibility and provider terms. Seek independent professional advice before entering any arrangement.
Want tailored sourcing?
Use the calculator for your scenario, then move into sourcing to compare, shortlist and apply.