
Invoice Factoring vs Invoice Discounting: Which Is Right for Your Business?
Invoice factoring and invoice discounting are the two most popular forms of invoice finance in the UK. They address the same problem — slow-paying customers — but work differently. The right choice usually comes down to control, confidentiality, cost and risk.
What Is Invoice Factoring?
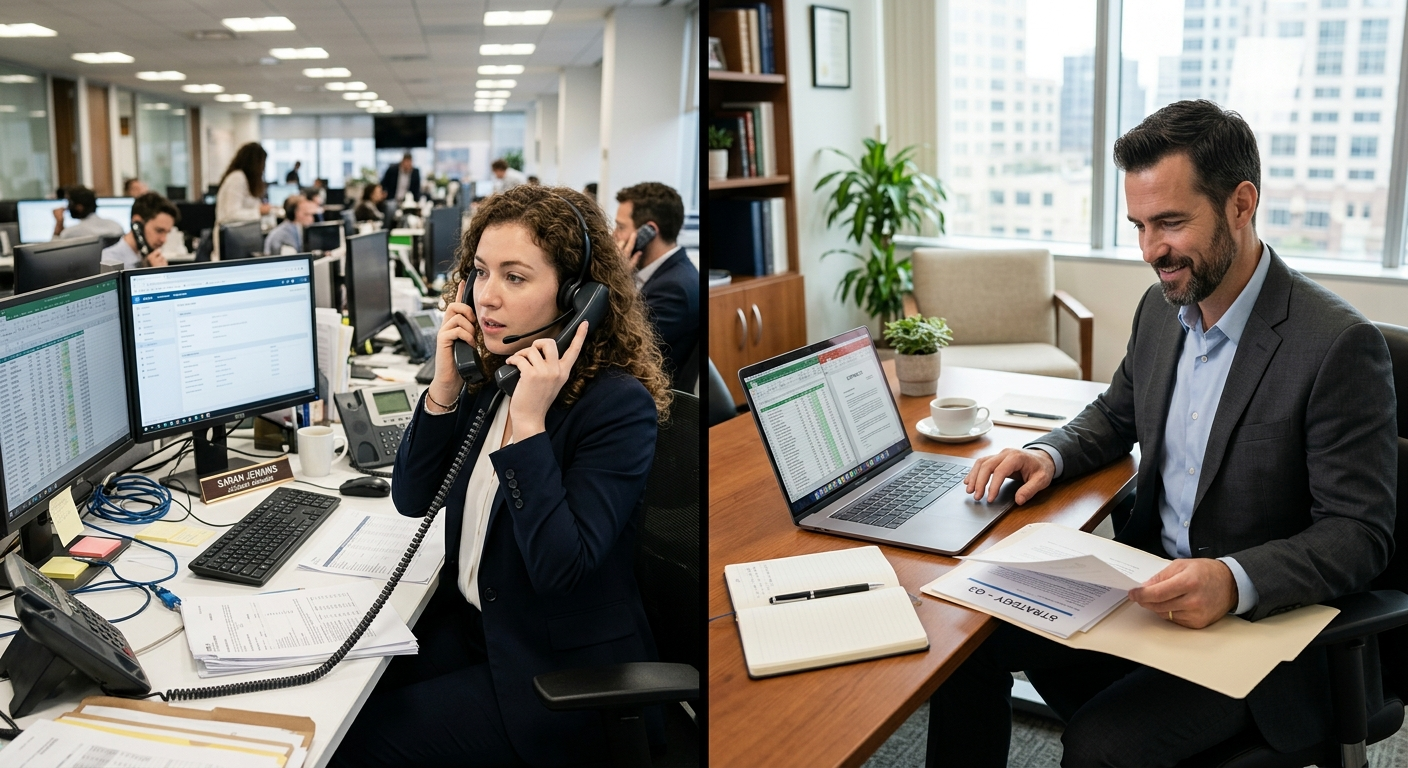
With factoring, the lender takes over your sales ledger and chases payment from your customers directly. Because collections are outsourced, your customers are usually aware a third party is involved. This can suit smaller businesses without a dedicated credit control team that would rather focus on running the business than chasing payments.
What Is Invoice Discounting?
With invoice discounting, you keep control of your own credit control and customer relationships. Your customers continue to pay you as normal and the facility is often confidential. Discounting is generally aimed at more established businesses with a track record of collecting payments reliably.
The Key Differences
Control: factoring hands collections to the lender; discounting keeps them in-house. Confidentiality: discounting is usually confidential, factoring is usually disclosed. Suitability: factoring can suit smaller or newer firms; discounting suits established businesses with strong credit control. Cost: factoring often costs more because it includes a collections service.
Recourse and Risk
Both can be offered on a recourse or non-recourse basis. With recourse, you repay the advance if your customer ultimately doesn't pay. Non-recourse shifts some or all of that bad-debt risk to the lender, usually for a higher fee. Weigh the cost of that protection against the risk to your business if a key customer failed to pay.
Which One Should You Choose?
If you want to outsource credit control and don't mind customers knowing, factoring may suit you. If confidentiality and control matter and you already collect efficiently, discounting is often preferred. Invoice discounting accounts for the large majority of the UK market by value, though factoring still supports thousands of firms. There is no single "best" option — it depends on your circumstances.
Compare Invoice Finance Options
Not sure which facility fits? Dynesourcer can help you compare factoring and discounting options across the market: https://www.dynesourcer.co.uk/mortgages/invoice-finance-sourcing
Final Thoughts
The right choice depends on your size, sector and how you want to manage customer relationships and risk. Comparing both properly helps you avoid paying for features you don't need.
Important information
Invoice finance for limited companies and LLPs is generally not FCA-regulated and typically falls outside the Consumer Credit Act 1974; sole traders/partnerships may have different protections. This article is not financial, legal or tax advice or a personal recommendation. Rates and figures are indicative and subject to change; finance is subject to status, eligibility and provider terms. Seek independent professional advice before entering any arrangement.
Want tailored sourcing?
Use the calculator for your scenario, then move into sourcing to compare, shortlist and apply.